PCE Inflation Report for August 2026: What to Watch
Comes out: Wednesday, September 30, 2026 at 8:30 a.m. ET
Published by: U.S. Bureau of Economic Analysis
131.6: the Fed's inflation gauge held steady in August
The inflation number came in at 131.6 for August 2026. This is the price gauge the Federal Reserve watches most closely. The Federal Reserve is the group that sets the country's interest rates. When it looks at inflation, this is the number it says it uses.
Last month the reading was 131.2. So this month is about the same. That means prices, on the whole, held steady from one month to the next.
A year ago the reading was 127.2. So compared with last year, the number is up. Prices are higher than they were twelve months ago, but the month-to-month pace has calmed down.
Here is why this matters for a home. When this number stays calm, the Federal Reserve feels less need to keep interest rates high. And when people expect rates to hold or ease, mortgage rates often follow. Even a small move in a mortgage rate changes the monthly payment on a $600,000 loan, so a calm inflation number is something a buyer, seller, or owner watches closely.
What to do with this: If you are buying, a steady inflation number is a reason to keep an eye on rates in the weeks ahead. If you are selling or refinancing, calmer inflation can help keep buyers active. Questions about what today's number means for your move? Call The Neuman Group at 954-228-5001.
A new inflation report comes out on Wednesday, September 30, 2026, at 8:30 a.m. Eastern time. It is called Personal Income and Outlays, and it is put out by the U.S. Bureau of Economic Analysis.
Inside that report is one number that matters more than most: the PCE price index. PCE stands for Personal Consumption Expenditures, which is just a measure of what prices are doing across the things people buy.
Why should you care? Because the Federal Reserve, the group that sets the direction for interest rates in the country, says this is the inflation number it watches most. When this number moves, expectations for interest rates move. And when those move, mortgage rates here in South Florida move too.
What this report actually measures
The PCE price index tracks the prices of things people buy: food, gas, rent, health care, and much more. When the index goes up a lot, that means prices are rising fast. When it barely moves, that means prices are close to steady.
You will also hear about core PCE. Core just means they take out food and gas prices, because those two jump around a lot from month to month. Core PCE gives a calmer view of where prices are really heading.
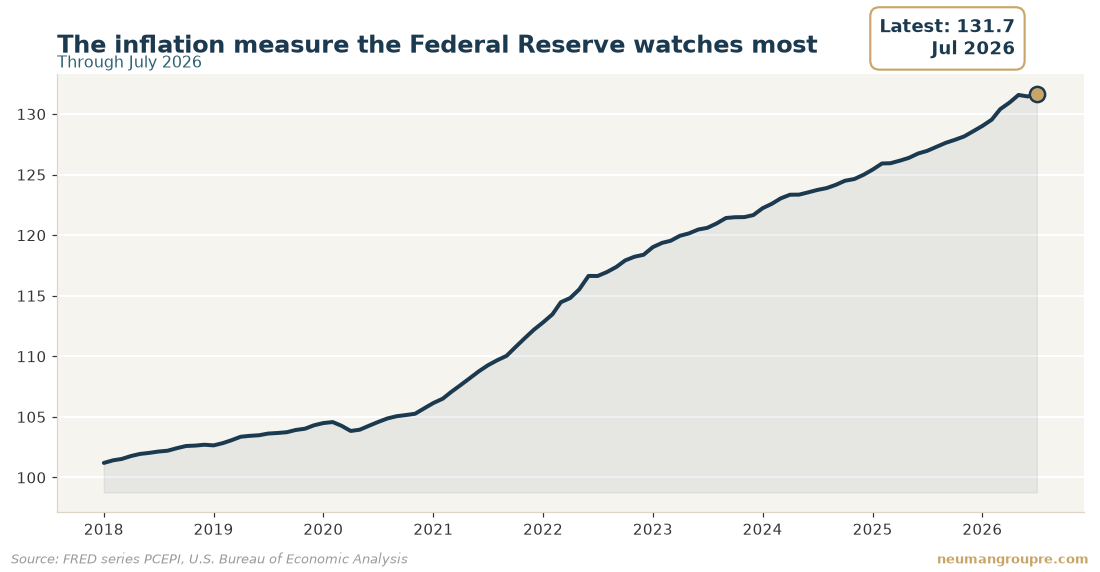
The index is set against a starting point of 100. A reading above 100 means prices are higher than they were at that starting point. The higher the number climbs, the more prices have gone up over time.
What the charts show right now
The chart above shows the price index at 131.7 for July 2026. The month before, it was 131.5. So from one month to the next, it was about the same. Prices did not jump, and they did not fall.
Zoom out to a year, though, and the picture is different. A year ago the index was 127.0. So over the past year, prices are up. That is the tug-of-war the Fed is watching: fairly calm month to month, but still higher than a year ago.
What it means for your mortgage payment
Mortgage rates are not set by this report directly. But they follow what people expect the Fed to do. If this report says prices are cooling, that makes lower rates more likely down the road. If it says prices are heating up, rates can stay high or climb.
Here is why that matters. On a loan of $600,000, even a small change in the rate changes your monthly payment by a real amount. Over 30 years, small differences add up to a lot of money. So a calm inflation number can quietly help buyers, and a hot one can quietly hurt them.
What it means for home prices
When rates are high, monthly payments are higher, so fewer people can afford to buy. That tends to cool demand and hold prices back. When rates ease, buying gets cheaper each month, and more buyers come back into the market. In South Florida, where prices are already high, this push and pull is easy to feel.
What it means for rent
Rent is part of what this report measures. If inflation stays warm, the cost of many things, including housing, tends to keep rising. If it cools, rent increases often slow down too. For an owner renting out a place, softer inflation can mean smaller rent hikes. For a renter, it can mean a little more breathing room.
How to read tomorrow's number
You do not need to guess the exact figure. Just watch the direction. Is the yearly number still climbing, or slowing down? Is the month-to-month change bigger or smaller than last time? Those two clues tell you more than any single decimal point.
Three things to watch
Questions people ask
What is PCE inflation in simple terms?
PCE stands for Personal Consumption Expenditures. It is a measure of the prices of the things people buy, from groceries to rent. When the number rises fast, prices are climbing. When it barely moves, prices are close to steady.
What is core PCE and why does it matter?
Core PCE is the same price measure with food and gas taken out. Those two prices swing a lot month to month. Removing them gives a steadier read on where prices are really heading, which is why the Fed pays close attention to it.
When does the report come out?
It comes out on Wednesday, September 30, 2026, at 8:30 a.m. Eastern time. It is released by the U.S. Bureau of Economic Analysis as part of the Personal Income and Outlays report.
How does this affect mortgage rates in South Florida?
The report does not set mortgage rates directly. It shapes what people expect the Fed to do with interest rates. If inflation cools, rates are more likely to ease. If it runs hot, rates can stay high or rise, which raises monthly payments.
Should I wait to buy a home until after this report?
One report rarely changes everything. It is one clue among many. It helps to know the direction prices are heading, but your own budget, the home, and your timeline matter more than any single number.
Every figure on this page comes straight from FRED (Federal Reserve Economic Data, Federal Reserve Bank of St. Louis) — series PCEPI. We publish these before the report lands so you can read the background while it is still quiet, then we add the actual number here the moment it is out.
Call 954-228-5001 or ask us for a free read on your property.